

Last week Treasury moved to push long yields down.
The effect lasted about a day. We now have learned how much capacity Bessent is prepared to commit to a second attempt.
Last Wednesday morning Treasury announced it would at least double its liquidity support buybacks, from $2 billion to at least $4 billion per operation, covering the 10-to-20 and 20-to-30 year sectors. The change takes effect September 9 and runs through November 4. A buyback is Treasury purchasing its own bonds on the open market, in this case older long-dated issues that trade thinly. The 30-year had reached 5.33% on Tuesday, its highest level in roughly nineteen years.
The market took it well at first. The 30-year closed Wednesday at 5.196% and the 10-year at 4.647%. By Thursday both had given it back, with the 30-year at 5.25% and the 10-year at 4.70%. Friday the long bond went higher still, to 5.273%.
The announcement faded because Treasury did not say where the funding would come from. The assumption was T-bills, which makes the operation a maturity swap of a few billion at a time. Bessent called it a Treasury Twist. A few billion does not move a stock of long bonds this size.
Monday supplied the missing piece. Two senior Treasury officials told CNBC the buybacks could be funded from the Treasury General Account, the government’s account at the Fed. It holds roughly $950 billion. Bessent built that balance out of tax receipts and has run it well above the $550 to $600 billion the prior administration maintained. The officials did not specify how much is available or when it would be used. The 10-year fell four basis points to 4.70% and the 30-year fell four to 5.23%.
Bessent has been explicit that he reads this as a liquidity problem. He said yields do not reflect fundamentals and pointed to thin conditions at the 30-year point specifically. Before assessing whether the buyback works, it is worth setting out what the operation is working against, because most of it is not liquidity.
Oil and AI is impacting the 30 Year Yield
A thirty-year yield is two things added together:
What buyers expect inflation to average over thirty years, and
What they require on top of that for lending until 2056.
Both are rising, for different reasons.
Oil. Hostilities with Iran began in late February. By mid-March the Strait of Hormuz was functionally closed, removing roughly 20% of global oil trade and forcing Gulf producers to cut output by 10 million barrels a day. The IEA described it as the largest supply disruption in history, with global production falling to four-year lows. Brent peaked above $109 in early April. A ceasefire brought prices back to pre-war levels by late June. Renewed US strikes in July reversed that, and Brent has traded in the mid-$80s since. Supply shocks raise the price level directly, and the Fed has no tool that addresses them.
Fertilizer. The same closure affects food on a longer lag. Roughly a third of the world's nitrogen fertilizer transits Hormuz, and the Middle East accounts for about 42% of global urea exports and 27% of ammonia. Nitrogen prices rose between 25% and 50% from late February to April. Nitrogen supports around half of global crop production and JPMorgan's July 24 report projects global food inflation rising from 2.8% in the first half of 2026 to roughly 5% in the first half of 2027, adding 0.3 to 0.6 points to headline inflation worldwide.
Two borrowers with inelastic demand for capital.
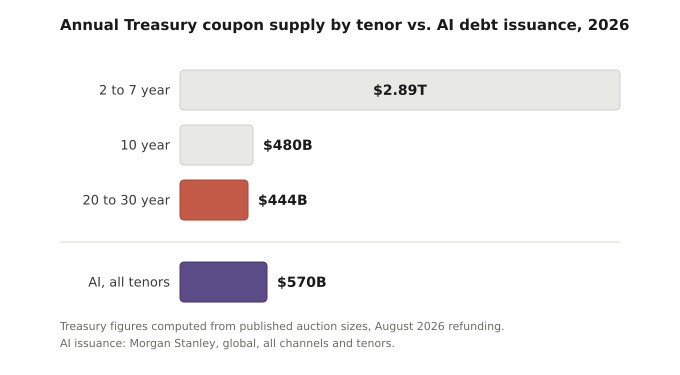
First is the federal government. Debt crossed $40 trillion and Treasury will borrow more than $2 trillion this year to fund existing obligations.Net interest was $971 billion in FY2025, up from $375 billion in FY2019.
The CBO has FY2026 at about $1.0 trillion, roughly $2.8 billion a day. Interest is now the third-largest line in the budget, behind Social Security and Medicare and ahead of defense. Through ten months of FY2026 it is running 10.6% above last year.
The gap between the average rate and the marginal rate is what carries this forward. The weighted average on marketable Treasury debt was 3.4% in July. The 10-year is at 4.70% and the 30-year at 5.23%. Maturing debt refinances at the higher number, so the average converges on the marginal over time and the interest bill rises without yields moving further. CBO estimates rates one point above baseline would add $3.2 trillion to interest costs over the decade, and projects net interest reaching $2.1 trillion by 2036.
Second is the AI buildout. The capital is going towards bonds in chips, and data centers. Capex guidance for 2026 runs to roughly $200 billion at Amazon, $175 to $185 billion at Alphabet, $80 billion at Microsoft, and $70 billion at Oracle. Operating cash flow is not covering it. Morgan Stanley puts global data center capex at $2.9 trillion through 2028 against about $1.4 trillion of hyperscaler cash flow, leaving $1.5 trillion for credit markets.
The five largest issuers sold $121 billion of bonds in 2025, against an average of $28 billion a year between 2020 and 2024. Barclays counted $218 billion globally through mid-July and expects $285 billion by December. Morgan Stanley’s broader count of AI-related debt issuance reaches roughly $570 billion this year, more than double last year. Private credit has supplied another $200 billion, up from near zero. The same five carry $662 billion of data center leases that have not commenced and sit off the balance sheet.
Tenor is the time until a bond matures and it is what makes this a thirty-year question rather than a five-year one.
This matters because a company borrowing at three years competes with Treasury bills and has no bearing on the long end. Oracle’s February offering extended to forty years. Alphabet issued a hundred-year bond. Forty-year corporate paper was uncommon until recently and is now a regular feature of the calendar, competing for the same buyers as the long Treasury.
Strategists have added AI issuance to the list of factors behind this month’s selloff. BofA attributes about 0.3 points of the ten-year move to corporate and mortgage supply combined. It is not the deficit’s equal. It is the newer contributor, and the one still scaling.
Oil raises the price level and the borrowing raises the price of duration, meaning what investors charge for accepting interest rate risk over long horizons. Both borrowers issue regardless of what capital costs, which leaves everyone else competing for the remainder. Rising Treasury yields also feed back into the federal interest bill, so the two effects compound.
The buyer base is thinning underneath both. Foreign central banks and sovereign funds were historically the steadiest source of demand at auction. They are down to about 12% of outstanding Treasuries and still declining. Auction data shows the same pattern by tenor: the thirty-year bid-to-cover was 2.29 in January against 2.85 for four-week bills.
Buybacks address the liquidity component. They do not address the other four.
One thing changes some of this picture, and is imminent.
Every figure in the credit section rests on an assumption about AI cash flows that has only ever been marked privately. The leases, the private credit, the forty-year paper. Anthropic filed confidentially on June 1 and is expected to list in October, with investors targeting a valuation above $2 trillion. That is the first deep public market price on frontier AI revenue.
We are watching it for what it says about the credit, not the equity. If public markets underwrite those cash flows at or near where private credit has assumed them, the spread on AI paper holds and the duration supply keeps clearing. If they underwrite them lower, that paper reprices, issuance slows, and one of the two borrowers in this memo steps back from the long end.